

Summary
Strong-Brand: Founded in 1748, one of the leading supplier of ceramic sanitary ware, eye-catching, high-quality tableware producer
Stable Growth: Steady revenue growth over the last ten years with a CAGR of 3.5%, EBITDA margins around 10-15% and ROIC at 15% in the last five years
Solid Balance Sheet: Low debt profile, and high liquidity of €260 million (cash + short-term investments) considering the market cap of around €500 million
Attractive dividend yield: Dividend track record spanning over 30 years, dividend CAGR (10y) of 11% with average payout ratio of 40%
Geopolitical Tensions and Fear of Recession: Key Challenges include rising interest rates and geopolitical tensions leading to a cooling of economic activities in the construction sector, increase in energy costs, particularly in European and German markets, and increased inflation negatively impacting consumer behaviour
Introduction of Villeroy & Boch
From small ceramic Producer to leading global Lifestyle Provider
Back in 1748, the luxuries of a modern home seemed like a distant dream when François Boch and his three sons embarked on their journey to craft ceramic tableware. Villeroy & Boch, founded in 1748 by François Boch, started as a small pottery workshop in Audun-le-Tiche (France), eventually evolving into a renowned manufacturer of affordable ceramics. In the 19th century, Jean-François Boch and Nicolas Villeroy merged their businesses to compete with English stoneware manufacturers.
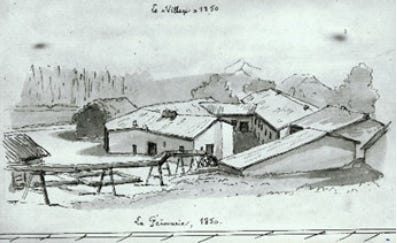
Throughout its 275-year history, Villeroy & Boch has navigated several political changes, world wars and market dynamics. Today, the company is one of the leading ceramic manufacturer, operating internationally across the globe and is diversified into sanitary ceramic wares and high-end luxury dinnerware.
Products & Customer Groups
Headquartered in Germany and products sold in around 125 countries, Villeroy & Boch’s business activities are broadly classified into two segments, Bathroom & Wellness and Dining & Lifestyle.
Bathroom & Wellness
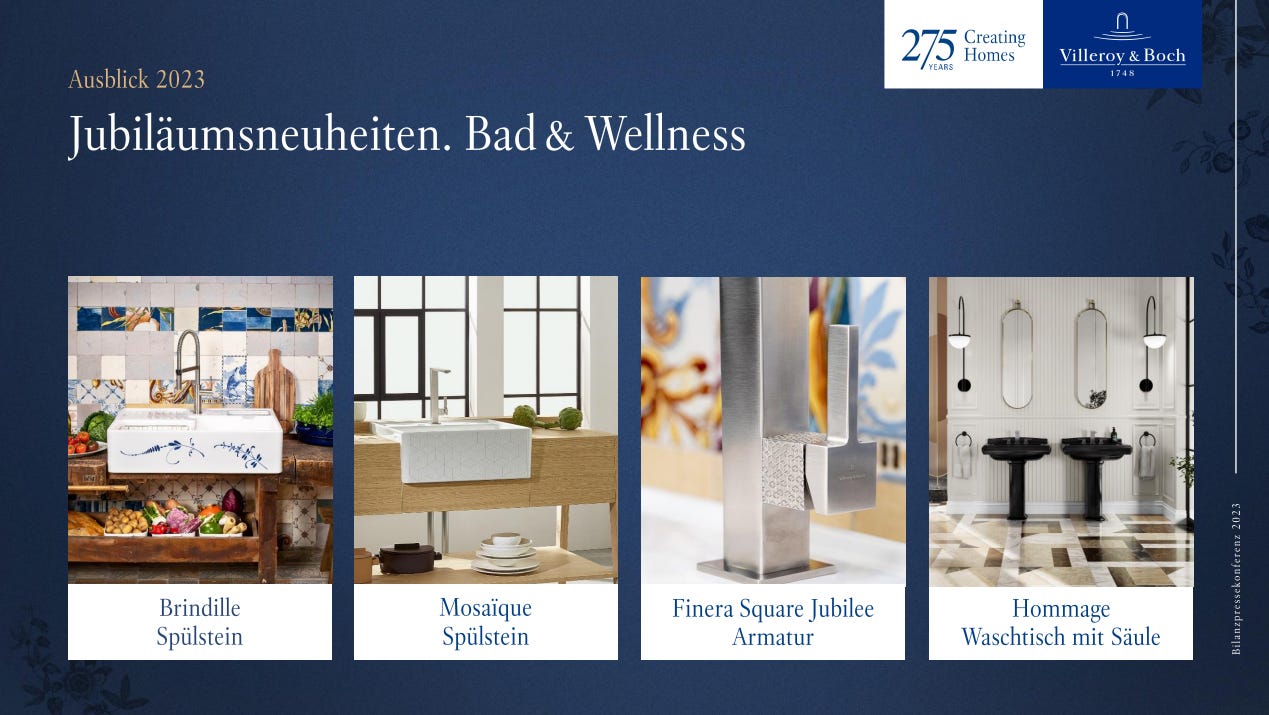
The Bathroom & Wellness segment accounts for two-thirds of the revenues and focuses on ceramic sanitary was as the core business and wellness products including WCs, shower toilets, bathtubs and shower trays, washbasins, bathroom furnitures, and whirlpools (in- and outdoor). To effectively address the needs of these different customer groups, the company adopts a two- or three-tier sales approach. This involves collaborating with retail and trade partners as well as planners, architects, and interior designers who play a crucial role in connecting the company's products with the end customers.
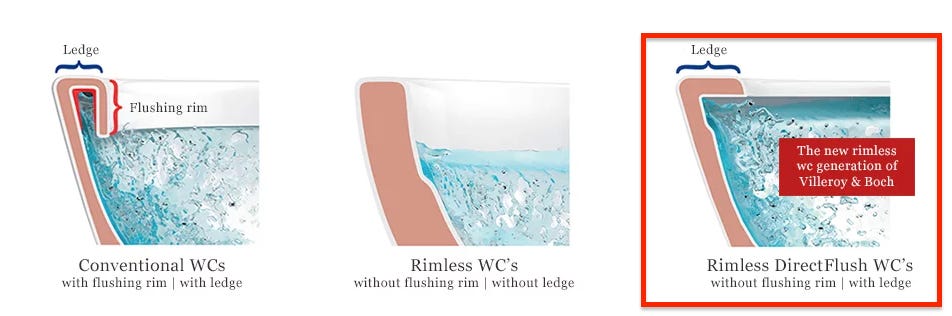
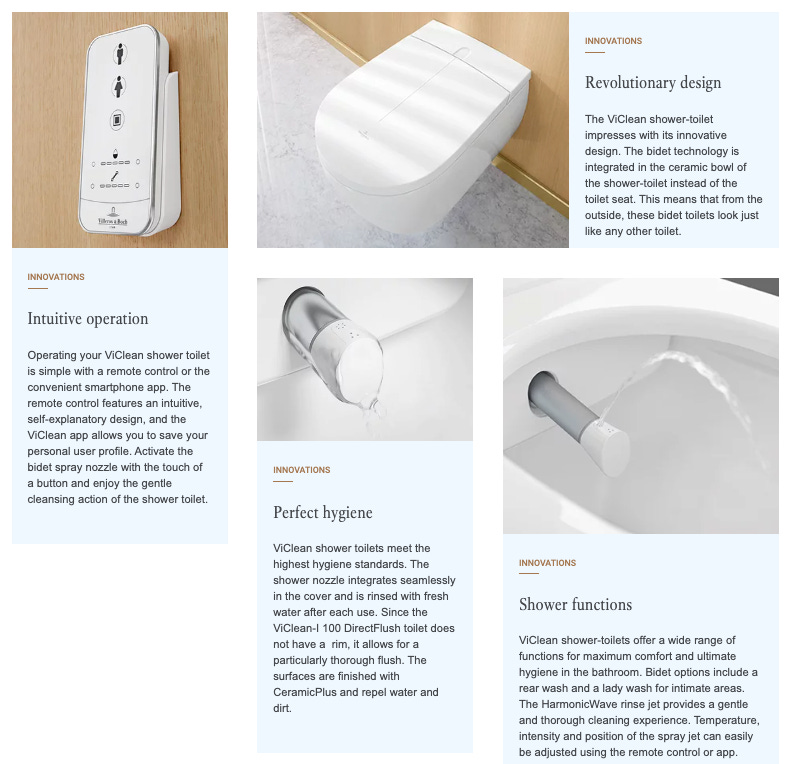
Some of the Villeroy & Boch’s innovation include products, such as the rimless DirectFlush WC or the ViClean 100 shower toilets, providing intimate cleansing and offering ultimate hygiene.
Dinning & Lifestyle
This segment makes one-third of the total revenue and includes high-quality and luxury dinnerware such as cutlery collections and home accessories.
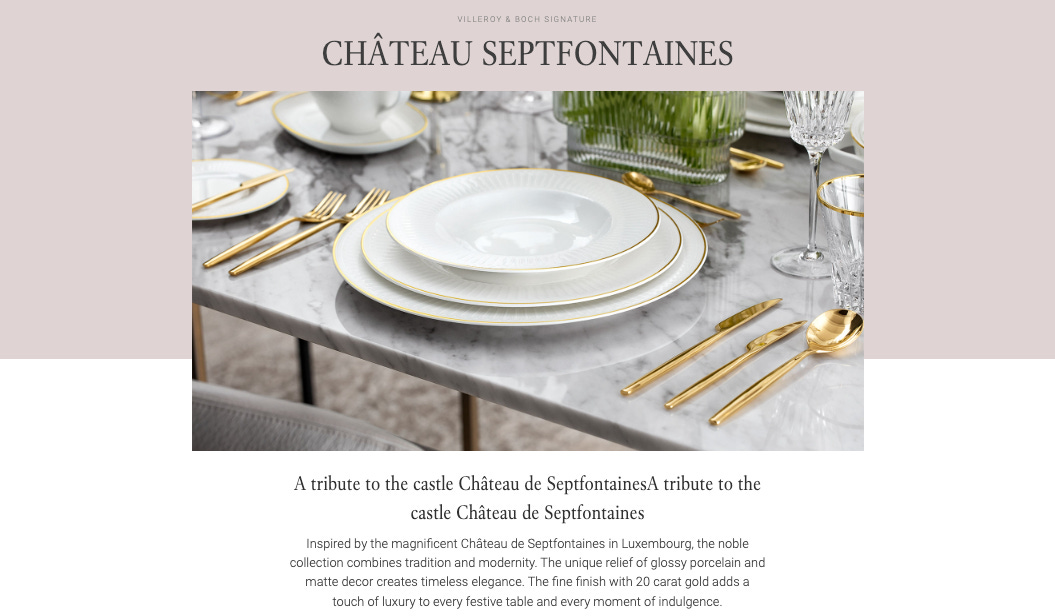
To make these premium offerings easily accessible to customers, the company employs a well-structured distribution network. In an B2C sales approach, customers can discover these products via large department stores, various e-commerce platforms and retail partners such as Amazon and Macy’s. In addition to these sales channels, the company successfully operates its own online shop which has proven to be a valuable platform especially during the recent years of the COVID-19 pandemic.
Management
The company boasts an experienced management team with almost all Members of the Management Board having served for more than a decade, with low management turnover in key functions.
Frank Göring, the current Chairman of the Management Board (CEO), has been with Villeroy & Boch since 1997, initially joining as a Marketing Director for the Bath & Kitchen segment. Over the years, he progressed to become a member of the board of management, responsible for the bath and wellness segment. Since 2007, he has served as CEO, marking more than a decade in this role.
Georg Lörz has a long history with Villeroy & Boch, joining in 2003 and serving in various Sales & Marketing roles until 2009. After almost a decade, he returned as CEO of the Bath and Wellness Division.
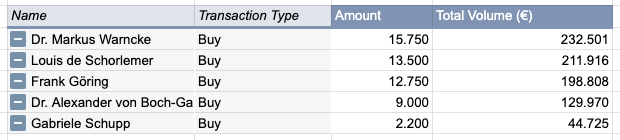
Dr. Markus Warncke, the CFO of the company since 2015, has been with Villeroy & Boch for over two decades, joining in 2001. Notably, he, along with the Frank Göring, has been actively purchasing Villeroy & Boch shares on the open market since 2016, with the most recent purchases occurring in March 2022.
SWOT Analysis
Strengths
Competency in Ceramics with 275 years of history, manufacturing know-how, product technology, customer relationships, access to distribution channels, capital intensity
Brand name, Villeroy & Boch, is associated with product quality and technical leadership in ceramic sanitary ware
Continuous Innovation with products such as DirectFlush-WC, ViClean-I 100 and TwistFlush and material innovations such as TitanCeram
Sound balance sheet with low debt profile and high level of cash + short-term investments of over €260 million considering the company's current market cap at around €500 million
Weakness
Cyclical Business with high dependency on the overall economic activity, private and public nonresidential and residential construction spending, consumer sentiment, commodity prices and purchasing power of households
Exposed to changes in input costs, including raw materials and energy (natural gas) components, and labor costs
Supplier concentration due to single sourcing for some of the raw materials due to no other available alternatives
Opportunities
Further Growth potential in APAC regions due demographic trends such population growth, urbanization, rising middle class
Increasing share of project business in the post-Covid era with hospitality industry showing signs of recovery, leveraging partnering opportunities with leading hotel chains and other companies
Expanding in other big construction markets such as United States due to geopolitical tension with Russia and China
Threats
European construction slowdown on the back of macroeconomic slowdown and sharp increase in interest rate, worsening in consumer sentiment,
Further escalation of geopolitical tensions threatening the outlook for global economy
High dependency of Bathroom & Wellness segment on the European, especially German construction activity and financing conditions
Shortage of skilled workers in sanitary industry, especially in Germany which could impact and limit further growth
Production Risk due to “grean deal” in EU, to become net-zero greenhouse gas emissions until 2050 resulting in increased cost for domestic production
Industry & Business Environment
Global Sanitary Market
The demand for sanitary ware products is continuously growing, driven by their essential role in residential, commercial, and public spaces. Ceramic sanitary ware, in particular, is highly favoured by end-users because of its durability, low maintenance needs, cracking resistance, and aesthetic appeal. This heightened preference for ceramic sanitary ware has led to an upsurge in demand across various sectors, including residential properties, hotels, industries, hospitals, and public establishments.
According to the latest industry research, the global Ceramic Sanitary Ware market size was valued at $46 billion in 2022 and is expected to expand at a CAGR of 8.53%, reaching $76 billion by 2028. Factors such as the rising population, urbanisation, and increasing disposable income of middle-class population and growth in awareness regarding sanitization and hygiene are supporting market growth.
The ceramic sanitary market can be segmented on the basis of product such as Toilet Sinks & Water Closets, Urinals, Wash Basins and application, residential (Single & Multifamily) and Commercial (Industrial, Hospitality, Retail & Offices)
Geographically, the Asia-Pacific-China (APAC) witnessed the fastest growth and is the largest market of ceramic sanitary ware, followed by Europe and North America. The massive industrial growth, in China in particular, the expansion of middle class income groups, infrastructural development and new product launches by key players in the region has as been fuelling the growth of the ceramic sanitary ware market over the past few years, and let to speed up the investments as well as local representation across major players like Geberit, Duravit, Villeroy & Boch and others.
Inflation, Slowdown in Construction, Geopolitical Tension
Villeroy & Boch operates in a highly cyclical business environment, where its Bathroom & Wellness segment is closely tied to the construction industry and economic growth prospects. Therefore, it is worthwhile to take a quick look into current development of the construction sector and its impact on the company's business.
The construction industry remains a significant global sector, contributing a substantial share to the Gross Domestic Product (GDP) in most countries. The worldwide construction market was estimated at $7.28 trillion in 2021 and is expected to reach $14.41 trillion by 2030, with a compound annual growth rate (CAGR) of 7.3% between 2022 and 2030. In Europe, the main market for Villeroy & Boch, approximately 80% of the total construction volume of €1.9 trillion was attributed to building construction. Residential construction and non-residential construction maintained their distribution at approximately 60% and 40%, respectively. Additionally, renovation projects continued to dominate new construction activities throughout the year.
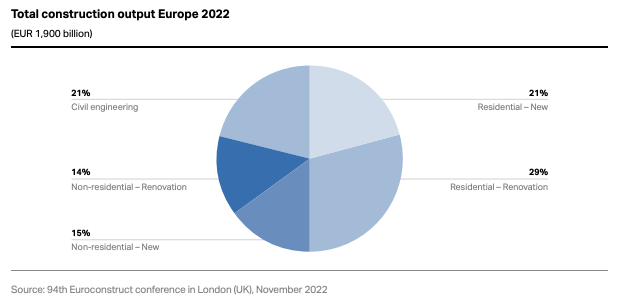
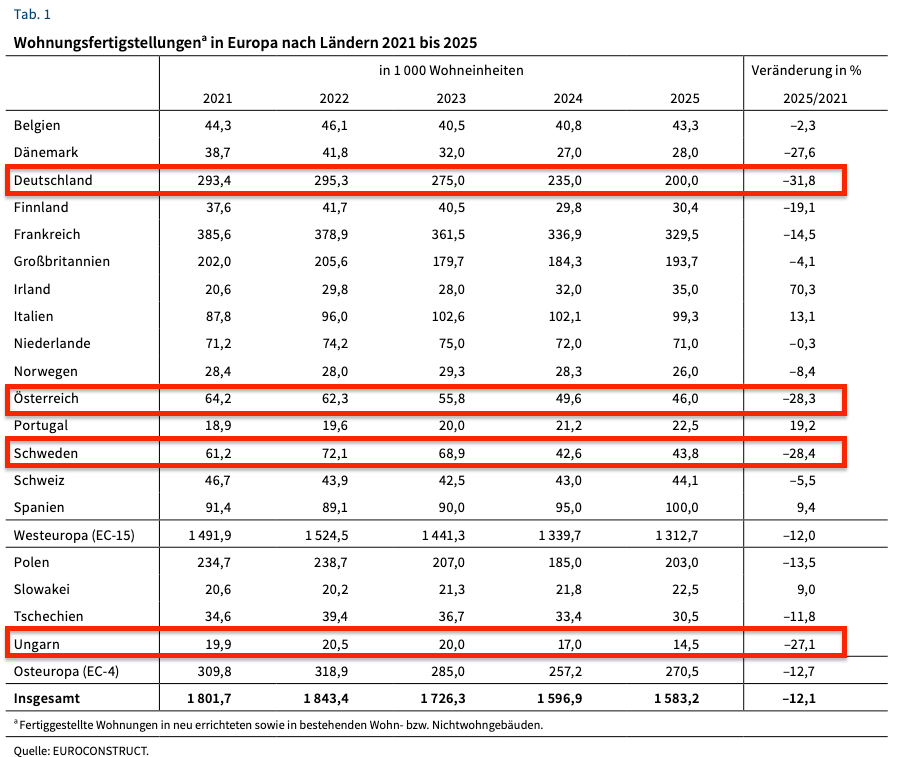
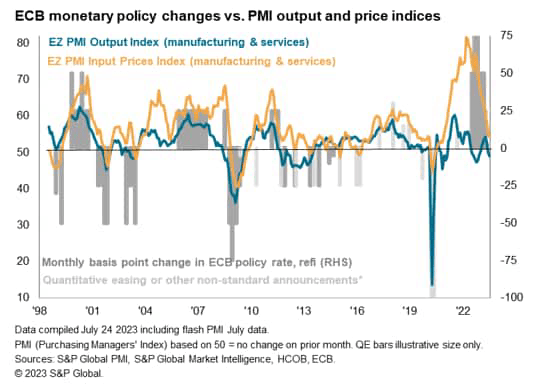
The construction sector experienced a slowdown in growth compared to the previous year, primarily due to the lingering impacts of COVID-19 recovery. The impacts by the interest rate turnaround in EU, which almost tripled from 1,2% to 4,6% between Jan 2022 to April 2023, and the increase in construction costs due to energy and raw material cost, puts the severe pressure on the overall construction industry, especially for residential construction, contributing to constraining growth in various markets. In the latest Euroconstruct summer conference in 2023, projections indicate a further slowdown in construction activity across Europe from 2023 to 2025. The residential construction sector in Germany and other European countries is expected to face notable challenges during this period, with an anticipated decrease of 31.8% in the German residential construction sector.
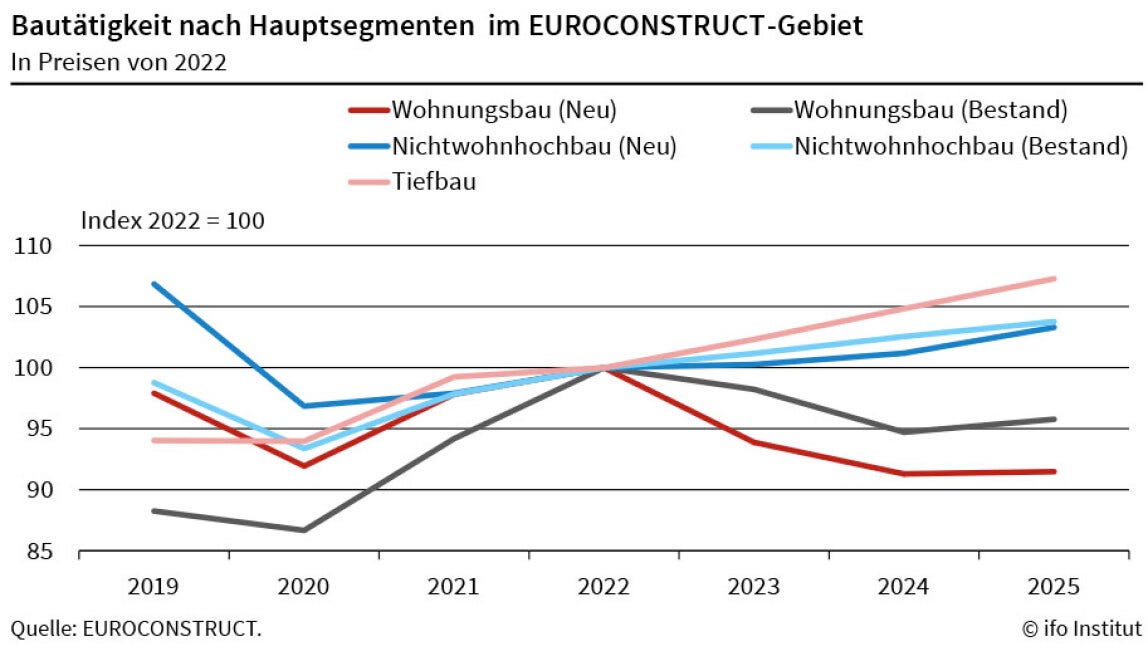
The construction of new non-residential buildings is experiencing only marginal progress, while renovation activities are showing robust growth until 2025. However, both segments are impacted by rising interest rates and stricter credit requirements, which also affect companies' willingness to undertake construction projects.
Due to its significant dependence on private consumer spending, the Dinning & Lifestyle business is particularly susceptible to various economic factors, including inflation and the purchasing power of households. These challenges have been evident in the last few months worldwide, with Europe and Germany being especially impacted.
Key Industry Players & Peers
The global ceramic sanitary ware market is characterized by its high fragmentation, with the presence of both global players and local manufacturers. Some notable global players in the market include Duravit (Germany), Geberit (Switzerland) - Europe's market leader in sanitary products, Toto (Japan) - a high-tech toilet manufacturer, and Grohe (Germany), which was acquired by Lixil Group (Japan).
It is worth mentioning that Geberit's acquisition of Sanitec in 2015, Finnish maker of toilets and bathroom ceramics, allowed them to expand their product portfolio to include bathroom ceramics and solidified their position as the European market leader for sanitary products. Additionally, the acquisitions of Grohe by Lixil in 2014 and Masco Corporation with a major stake of 68% in Hansgrohe underscore the trend favouring the creation of complete product portfolios in the bathroom & wellness segment. This strategy aims to provide customers with a comprehensive range of offerings from a single source. As a result, larger players are emerging in the market, intensifying competition and putting pressure on Villeroy & Boch to maintain its market share.
In summary, Villeroy & Boch operates in a highly competitive and fragmented industry, facing challenges such as high raw material costs and a slow construction economy in Europe, especially in Germany, it’s key market.